Signals Across Markets
Markets continuously provide information to investors, but sometimes the message becomes clearer when several markets are viewed together. Recently, the relationship between interest rates, equities, foreign exchange rates, and scarce assets like gold has become particularly noteworthy. These markets reacted after the US Treasury announced an expansion of its buyback program for long-term government bonds.
Long-term interest rates have remained elevated amid several structural risks, including persistent inflation uncertainty, potential energy shocks, and relatively large fiscal deficits. The Treasury’s buyback program is designed to improve liquidity in the government bond market. At first, long-term interest rates declined as the Treasury conducted its purchases. However, the initial reaction was short-lived, suggesting that larger forces may be at work that improving Treasury market liquidity cannot address.
Sustained government deficits, combined with greater inflation uncertainty, can cause interest rates to increase, currencies to weaken, and demand for scarce assets to rise. Watching these markets move together can tell investors something important about broader shifts across financial markets. Investors require compensation for inflation, economic uncertainty, government borrowing, and the risk of locking money away for decades. When investors sense they are no longer being fairly compensated, they can turn to assets offering greater productive or scarcity value.
Investors often turn to equities or gold when bond returns may not adequately compensate them for inflation and other long-term risks. Equities offer productive value through ownership in businesses and their future earnings, while gold derives part of its appeal from scarcity. Gold reacted positively after the Treasury made its buyback plans known. This doesn’t mean financial markets are broken. Instead, it can indicate that investors are placing greater value on assets offering productive or scarcity value.
For investors, the lesson is less about predicting which market will move next and more about diversification. Equities represent ownership in productive businesses, bonds provide contractual payments, and hard assets can respond differently to changes in inflation, currencies, and interest rates. Diversification’s real value comes from owning assets that respond differently to the same economic pressures, differences that can become especially valuable when the economic environment is changing.
Geopolitical
Geopolitical risk has moved back to the center of the market narrative, with conflicts involving Iran and Canada creating pressure through energy prices, tariffs, interest rates, and investor confidence. Neither situation appears close to a resolution, suggesting markets may need to absorb continued volatility rather than quickly return to the status quo. The Iran conflict continues to threaten oil flows through the Strait of Hormuz. A fraction of the pre-conflict amounts of oil are currently moving through the strait, which continues to pressure oil prices. Iran’s proposed 5% to 7% service fee on oil shipments would be difficult to implement under international maritime law, making any near-term agreement more likely to be a short-term fix.
Higher energy prices continue affecting financial markets. The US Strategic Petroleum Reserve has fallen below 300 million barrels, while the intermediate and long-term Treasury yields have shot up. Markets also increased the probability of a Fed rate increase, highlighting how quickly geopolitical developments can influence inflation and monetary policy expectations.
The US-Canada trade dispute has also escalated, with the US imposing tariffs of up to 50% on Canadian imports and Canada responding with additional tariffs. The direct trade exposure is relatively narrow, but the impact could be significant for concentrated industries such as autos, steel, lumber, and furniture. Canada also supplies roughly 60% of US crude-oil imports, along with other important resources, giving it meaningful leverage.
The longer these disputes continue, the greater the risk that temporary disruptions become permanent changes in supply chains and trade relationships. Continued geopolitical pressure could keep inflation elevated, Treasury yields higher, and markets more volatile even if the broader economy remains resilient.
Inflation & Jobs
Inflation remains mixed, with some improvement in consumer prices but continued pressure at the producer level. The core Consumer Price Index, or CPI, rose 2.5% year over year for the month of July, down from 2.6% in June and 2.9% in May. However, the core Personal Consumption Expenditures, or PCE, index remained at 3.3%, and headline PCE increased to 3.7% annually as of July. This is all well above the Fed’s 2% target, with higher energy prices, tariffs, and trade tensions potentially slowing further progress.
Producer prices are adding to the uncertainty. The August Producer Price Index, or PPI, increased 0.4% for the month and 5.4% year over year. Although the monthly core reading was slightly better than expected, the elevated annual figures suggest businesses are still facing significant cost pressures. The key question is whether companies absorb these costs or pass them on to consumers. On a brighter note, the labor market is showing more resilience than expected.
“The next CPI report will be an important swing factor, with softer inflation supporting a pause and renewed price pressure strengthening the case for tighter policy.”
Employers added 162,000 jobs in August, nearly three times the consensus estimate, while unemployment remained at 4.1%. Wage growth remained relatively firm, suggesting the labor market is steady but uneven. Stronger hiring and persistent inflation have shifted expectations toward Fed rate increases. The next CPI report will be an important swing factor, with softer inflation supporting a pause and renewed price pressure strengthening the case for tighter policy.
The broader fiscal environment adds another source of uncertainty. Federal debt has surpassed $40 trillion, or roughly 122% of GDP. Persistent deficits, mandatory spending, and rising debt-service costs could increasingly limit policy flexibility.
Federal Reserve
The Federal Reserve entered Jackson Hole with inflation still well above its 2% target and policymakers divided over whether additional rate increases are needed. The key question is whether current policy is restrictive enough to bring inflation back to target. Some believe that current policy can support gradual disinflation, particularly as higher long-term bond yields tighten financial conditions. Yet, the concern is that inflation has remained above target for more than five years, increasing the risk that expectations become less anchored.
Chairman Warsh emphasized that inflation remains the Fed’s primary concern and questioned whether financial conditions are restrictive enough. Following his remarks, the market expectation for future rate hikes increased. Fortunately, the broader economy remains resilient, giving the Fed more flexibility to focus on inflation. Capital expenditures and consumer spending have been on the rise. Further, profit margins remain elevated, and the labor market was described as stable and consistent with full employment. However, tariffs, oil prices, supply chains, and geopolitical developments remain important risks.
“The Fed may be changing how it communicates rather than fundamentally changing its policy framework.”
The Fed may be changing how it communicates rather than fundamentally changing its policy framework. Warsh argued that forward guidance has “outstayed its welcome,” favoring greater flexibility around future decisions, while reaffirming the 2% inflation target and PCE as the preferred inflation measure. The focus therefore remains on incoming data rather than a predetermined path for rates.
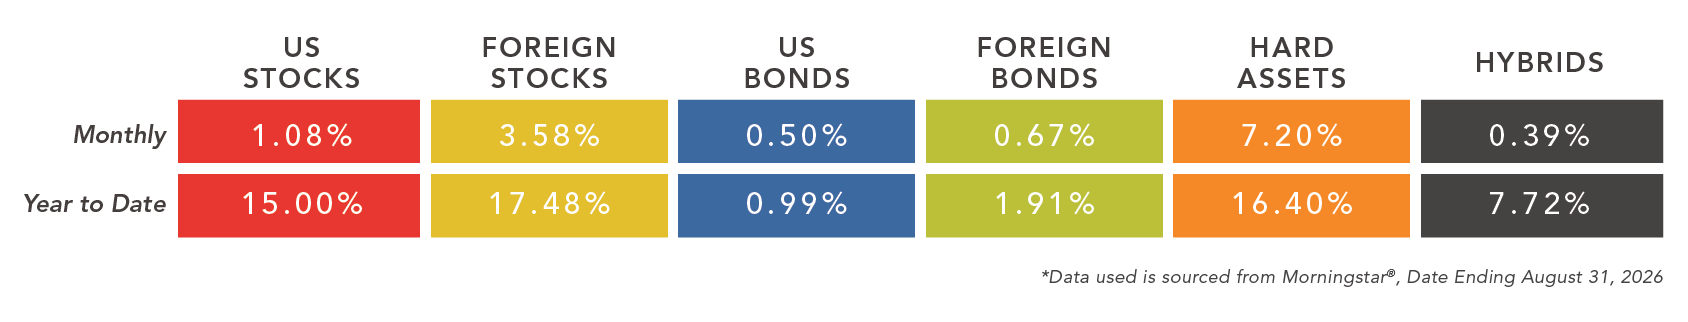
Stocks
The equity market continues to benefit from exceptionally strong corporate earnings, with the majority of US large cap companies beating expectations. However, market leadership has shifted significantly within technology, with software stocks outperforming semiconductors by nearly 50 percentage points since late June as investors become more selective about the AI opportunity. AI investment remains a major long-term growth opportunity, but the estimated multi-trillion-dollar infrastructure spending through 2028 raises questions about leverage and financial stability.
In August, US large caps outperformed small and mid cap markets. Yet, foreign equities outperformed the US markets. The equity markets continue to experience rotation both geographically and by industry. Yet, overall, global equities continued to add total return for the month, bringing year-to-date returns above long-term averages.
The outlook remains constructive as long as earnings estimates continue to rise, but higher oil prices, additional Fed rate increases, and questions about whether AI investment can generate sufficient returns represent important risks.
Bonds
Long-term Treasury yields have risen to levels not seen in nearly two decades, with the 10-year yield around 4.74% and the 30-year near 5.33%. This has been driven by government borrowing, higher oil prices, resilient economic growth, and growing demand for capital from AI investment.
Long-term yields have increased independently of Fed rate change expectations, suggesting investors are demanding more compensation for fiscal and economic uncertainty beyond short-term monetary policy.
Treasury auctions and reduced foreign demand, particularly from Japan, are reinforcing the pressure on long-term rates, while government buybacks are unlikely to address the underlying supply and deficit concerns. Higher yields will likely increase borrowing costs for households, businesses, and the government while putting pressure on bonds and higher-valuation stocks. But from a pure investment standpoint, higher bond yields can create more attractive income opportunities for new bond investors.
High yield bonds and bank loans continue to display strong total returns, outperforming most of the higher quality sectors yet again in the month of August. Year-to-date returns of these lower-quality sectors generally stand in the 2% to 3% range, which represents some of the more attractive returns in the broader bond market.
© Advisory Alpha. Registration with the SEC or a state does not constitute an endorsement of the firm by regulators, nor does it indicate that the adviser has attained a particular level of skill or ability. This content is for informational purposes only and does not intend to make an offer or solicitation for the sale or purchase of any securities. Investing involves risk, including the potential loss of principal. No investment strategy, such as asset allocation or diversification, can guarantee a profit or protect against loss in periods of declining values. All investment strategies involve risk and have the potential for profit or loss. Changes in investment strategies, contributions or withdrawals, and economic conditions may materially affect the performance of your portfolio. There are no assurances that a portfolio will match or outperform any particular benchmark. Investors should carefully consider the investment objectives, risks, fees, and expenses before investing. Any financial services firms referenced in this material do not provide tax or legal advice. Please consult with your tax or legal professional regarding specific issues prior to making a tax or legal decision.
The performance information presented in the asset category section of this report is based on equal-weighted averages of the following Morningstar Categories: US Stocks (US Fund Large Blend, US Fund Mid-Cap Blend, US Fund Small-Blend), Foreign Stocks (US Fund Foreign Large Blend, US Fund Foreign Small/Mid Blend, US Fund Diversified Emerging Mkts), US Bonds (US Fund Intermediate Government, US Fund Inflation-Protected Bond, US Fund Corporate Bond, US Fund High Yield Bond, US Fund Bank Loan), Foreign Bonds (US Fund World Bond, US Fund Emerging Markets Bond), Hard Assets (US Fund Commodities Precious Metals, US Fund Commodities Energy, US Fund Global Real Estate, US Fund Real Estate), Hybrid Assets (US Fund Convertibles, US Fund Preferred Stock).
© 2026 Morningstar. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete, or timely. Neither Morningstar nor its content providers is responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results. Morningstar category data is provided for illustrative purposes only to demonstrate a hypothetical investment vehicle represented by a group of similar investments. Morningstar category data is an aggregation across actual funds contained in the category, but it is not possible to directly invest in a category. Index returns are provided for illustrative purposes only to demonstrate a hypothetical investment vehicle using broad-based indices of securities. Unmanaged indexes are not available for direct investment. All data shown does not include internal fund expenses, trading costs, financial advisor fees, commissions, or taxes. This information is not intended to predict the performance of any specific investment or security. Past performance is no guarantee of future results.
Bureau of Labor Statistics. Unemployment Rate, Total Nonfarm Employment, Labor Force Participation, Consumer Price Index, Producers Price Index. www.bls.gov. United States, Department of Commerce, Bureau of Economic Analysis. Personal Consumption Expenditures, Gross Domestic Product, Consumer Spending, Personal Income, and Outlays. www.bea.gov. Federal Reserve. Fed Funds Rate, Fed Funds Target Range, Minutes of the Federal Open Market Committee, Board of the Federal Reserve System Calendar. www.federalreserve.gov. Trump, Donald. @realDonaldTrump. Truth Social.